Capacity constraints are holding back near-term growth at Penang technology companies even as order books climb to record levels, Phillip Capital Research said after a visit to the state.
The research house met 10 companies during its Penang trip, covering metal fabrication, aluminium processing, test equipment, engineering support services, environmental technology and electronics manufacturing services, The Star reported. Long equipment and material lead times are limiting production ramp-ups and order fulfilment.
Computer numerical control machines typically take six to 18 months to arrive, while raw materials take five to seven months to procure. Companies are bringing forward machine orders and capital expenditure, qualifying alternative suppliers and building material buffers, yet shortages in power supplies, alloy and copper components persist.
In some cases overseas suppliers cannot meet full order quantities, leaving local technology firms unable to fulfil outstanding orders. The pressure is plain on the factory floor, where some manufacturers report no room left to expand.
“Our capacity is now maxed out, no more floor space,” AMS Advanced Material Bhd managing director Keith Keh Teng Yang told The Edge, adding that mezzanine floor space would already be in use if compliance rules allowed it. Automated test solutions firm THMY Holdings Bhd has filled the new factory completed in January last year and is building a larger one, targeted for completion in the first half of 2028.
Demand is not the problem. Phillip Capital Research said growth visibility has strengthened across the sector, with most companies reporting improving demand trends and expanding customer pipelines. Order books and purchase orders sit at or near record levels, with delivery schedules extending through 2027 and in some cases into 2028.
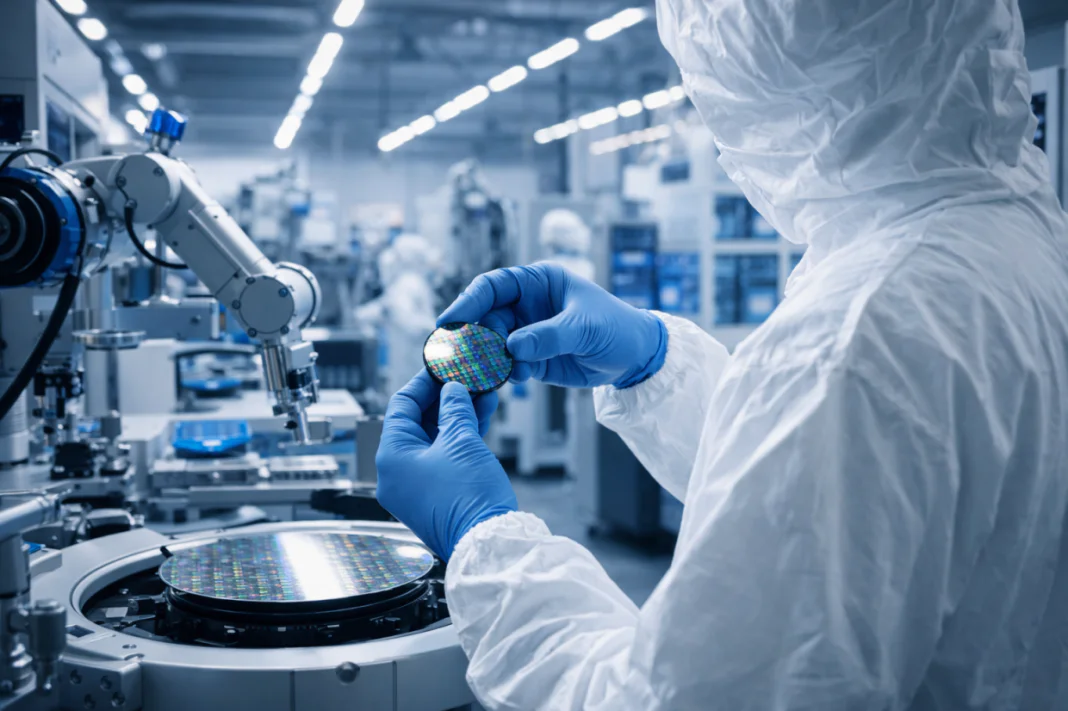
Four drivers underpin the demand: artificial intelligence chip and advanced packaging programmes, data centre buildout, wafer fabrication equipment capacity expansion, and the relocation of front-end equipment manufacturing into Malaysia. Utilisation ranges from 60% to 70% at less-used facilities to near-full capacity elsewhere, and several companies are already running second shifts.
Near-term earnings remain subject to supply constraints, slower capacity ramp-ups and initial margin dilution from new capital expenditure, the research house said while reiterating a neutral stance on the technology sector. It prefers companies with direct artificial intelligence and data centre exposure and clear earnings visibility.
Frontken Corp Bhd is a preferred pick for its front-end semiconductor exposure and direct linkage to TSMC. UWC Bhd is the other, for its order book visibility and rising front-end semiconductor exposure. UWC holds an outstanding order book of RM350 million, 90% of it semiconductor-related, and management targets a front-end mix of 70% to 80% within three years against 45% now.
Phillip Capital Research also flagged UWC’s appointment as the first Asian contract manufacturer for a new United States wafer fabrication equipment customer relocating production to Asia. Initial work covers deposition and wafer inspection equipment, with first shipments scheduled for March 2027 and volumes projected at 10 to 15 units per quarter once capacity expands. Early customer support includes RM40 million in materials and RM10 million in test equipment consigned to the group.
The minimum wage hike carries limited near-term impact, the research house added, because operators are generally paid above the minimum wage and higher volumes and pricing adjustments should offset the extra cost.
Risks named include a global economic slowdown, rising input costs, depreciation of the ringgit against the US dollar, and a reescalation of the United States and Iran conflict disrupting supply chains. The wider Penang supplier network is absorbing part of the strain, with players passing portions of orders to nearby partners and even rivals when their own lines are full, a practice clustered around Bayan Lepas and Batu Kawan.