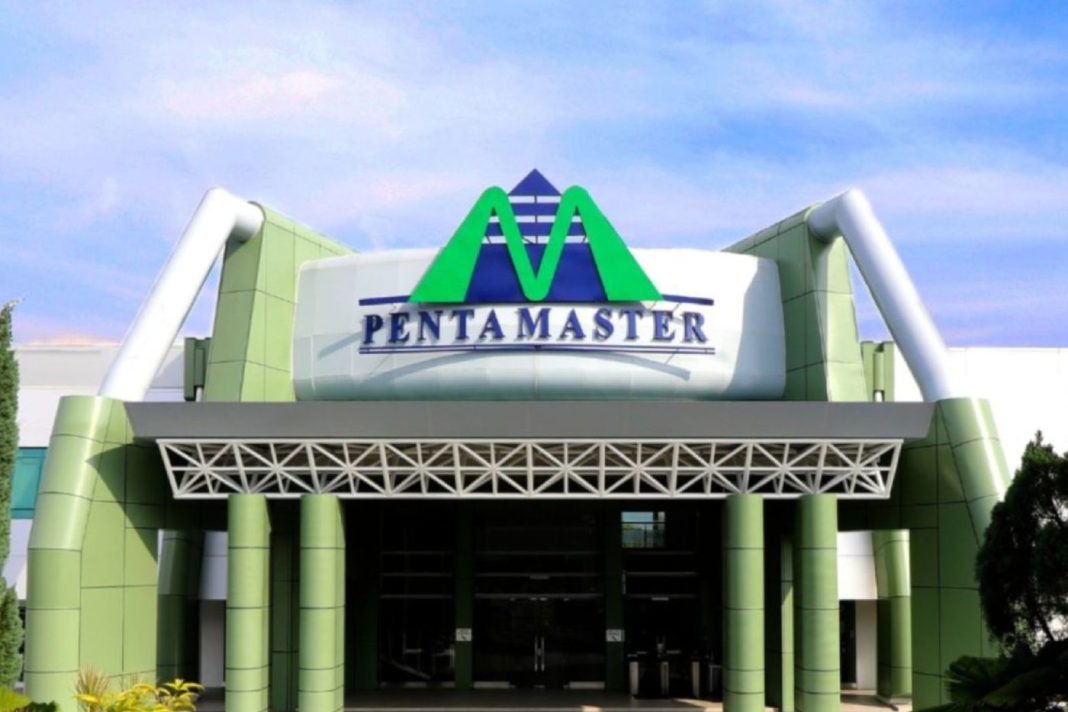
Pentamaster Corp Bhd is working through a near-record RM520 million orderbook that RHB Research expects to carry its earnings higher in the final quarter of 2026 and through financial year 2027, NST reported.
Medical equipment makes up 45 per cent of the orderbook, AI computing 30 per cent, consumer and industrial products 10 per cent and other segments the remaining 15 per cent.
RHB Research said demand for advanced AI and high-performance computing testing should keep the group’s advanced packaging test tools, sold under its 9 Samurai programme, moving into FY2027. The group has also secured a tax incentive covering 70 per cent of statutory income from advanced packaging and advanced photonics equipment in its automated test equipment segment.
Pentamaster is bringing an extra 120,000 square feet of unused space at its Campus 3 facilities into operation to support future manufacturing, the research house noted.
For the nine months to September 2026, core net profit rose 10.1 per cent year on year to RM49.2 million while revenue gained 37.9 per cent to RM585.3 million. Core profit met only 62 per cent and 66 per cent of RHB’s and consensus full-year forecasts, held back by an effective tax rate of 19.5 per cent against a tax credit a year earlier, after an earlier incentive expired.
Phillip Research reads the same results with more caution. The house kept a hold call and cut its target price to RM5.19 from RM5.55, The Star wrote, pointing to uncertainty over the renewal of tax incentives for the factory automation solutions segment and to continued losses in healthcare. It put 9M26 core net profit at RM45 million after stripping out a RM15 million unrealised foreign exchange gain and a RM3 million forward contract loss, below its and consensus full-year forecasts at 59 per cent and 60 per cent.
RHB Research trimmed its FY2026 earnings forecast by 9 per cent for a higher assumed tax rate but left FY2027 and FY2028 unchanged. It kept its buy call and its RM6.32 target price, based on an unchanged 36 times FY2027 price-earnings ratio. Phillip’s lower target rests on 39 times 2027 estimated earnings per share.
Factory automated solutions remained the main growth driver, with third-quarter revenue up 72.3 per cent year on year to RM171.6 million, or 63 per cent of quarterly revenue. Automated test equipment revenue rose 30.7 per cent to RM50.6 million, with electro-optical solutions contributing 23 per cent and AI compute 5 per cent. Healthcare revenue fell 39 per cent to RM5.9 million on weaker medical device sales.
Neither research house said when a decision on the factory automation tax incentive is expected.